The two kinds of Lake District car park
Five years of the Authority’s own parking figures say something you can act on: the Lake District doesn’t get busy evenly. Beech Hill sells 14.4× as much parking in August as in January; High Dam barely notices the season at 1.9×. Same National Park, same weather — the difference is what people came to do. And once you can see where the crowd actually goes, the useful question stops being where is everyone and becomes where else could I park.
What this means if you are the one parking
Two things follow from the figures below, and neither of them is about what time to arrive. This data cannot tell you that — it counts months, not hours — and the method section says so plainly.
In summer the pressure is concentrated, not spread. Hawkshead alone takes 75,706 transactions in an average year against Threlkeld’s 608. Most of the estate’s August load lands on a short list of well-known places, and the 20 Authority car parks are only a fraction of the parking in the National Park.
In winter the two kinds pull apart. The lakeside and visitor-centre car parks go quiet in a way they never are in summer. The ones walkers use carry on at something much closer to their normal trade — so a February trailhead may be busier than you expect, even while the honeypot down the road is empty.
This is the reason the site has a parking map. Reading where the Authority’s own demand concentrates is what sent us looking for everywhere else — and there is a great deal of everywhere else. The map now carries 968 places to leave a car for a walk, in the National Park and around it, each with what is known about access, surface and charges.
Tickets sold, month by month
The Authority sells parking at 20 car parks across the National Park. Every ticket is a row in this data: April 2021 to March 2026, month by month, released under LDNPA, FOI/2026.486 (opens in new tab) on 22 July 2026.
The figures
| Month | Transactions |
|---|---|
| January | 36,581 |
| February | 61,371 |
| March | 86,994 |
| April | 126,395 |
| May | 138,228 |
| June | 159,409 |
| July | 224,434 |
| August | 278,017 |
| September | 189,858 |
| October | 138,073 |
| November | 72,479 |
| December | 52,723 |
The two kinds
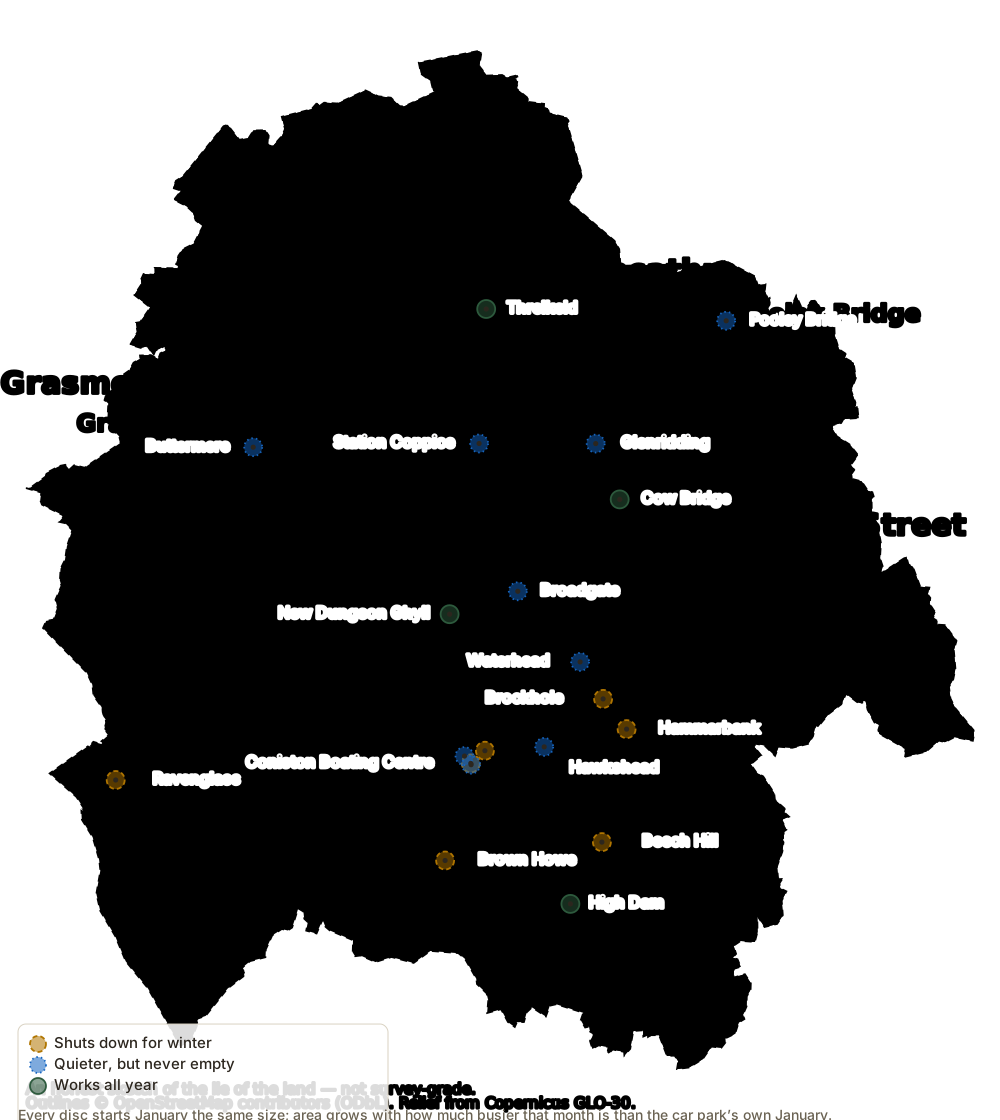
Rank the car parks by how much busier August is than January and the estate pulls apart. At one end, 7 car parks do almost all their trade in summer — Beech Hill sells 14.4× as much parking in August as in January, though it is open and selling tickets through the winter like the rest. At the other, 4 carry on much as normal, High Dam lowest of all at 1.9×.
The ones in the middle
The tidy split is not the whole story, and the exception is the interesting part. 9 of the 20 sit between the two ends — the largest group of the three, and mostly the village and lakeside car parks: Waterhead, Ruskin Avenue, Hawkshead, Glenridding, Station Coppice, Buttermere, Coniston Old Station, Pooley Bridge and Broadgate.
The flattest band is smaller and holds a different set of places entirely: Cow Bridge, New Dungeon Ghyll, Threlkeld and High Dam.
What I make of it is that a car park’s year tells you who uses it. The ones that hibernate are the ones you visit for the place — boat hire, a visitor centre, an ice cream on a lakeshore. Those are August propositions and they don’t pretend otherwise. The ones that hold steady are the ones you park at in order to go and do something: Cow Bridge, New Dungeon Ghyll, Threlkeld. Walkers don’t wait for the weather, so those car parks never really empty.
If you’re planning a February walk that cuts both ways. The lakeside honeypots will be quiet in a way they never are in summer — and the trailhead you assumed would be empty because it’s winter may be doing something much closer to its normal trade.
A check against a different dataset
Everything above rests on one dataset and one reading of it, so it is worth asking whether anything else points the same way. How much people search for the fells has nothing to do with the Authority’s parking figures. If a car park’s year really does say something about who uses it, the ones that empty in winter ought not to be near the fells people look up. On this evidence they are not.
| Band | Median nearby search demand |
|---|---|
| Much the same all year | 8,220 a month |
| Quieter in winter | 6,680 a month |
| Mostly a summer car park | 300 a month |
The gap is clear at 5 and 8 km but not at 3 km — at that range most of these car parks have no Wainwright summit near them at all, so there is little for the comparison to bite on. The test behind that is narrower than the table: it sets the 7 car parks that shut for winter against the other 13, and measures the gap between their medians against all 77,520 ways those 7 could have been drawn from the 20. At the wider distances the difference is larger than chance comfortably explains (p = 0.106 at 3 km, p = 0.004 at 5 km, p = 0.004 at 8 km).
What it does and does not settle. This is a small sample and one way of measuring nearness, so it is a supporting observation rather than a result in its own right. What can fairly be said is that the reading above is not ours alone: a measure with no connection to the parking data leans the same way. The places that empty in winter tend not to be near the fells; the ones that stay busy tend to be.
What it does not show, which matters just as much. Search demand does not predict how busy a car park is. That relationship changes sign depending on how far we look (-0.00 at 3 km, +0.14 at 5 km, +0.03 at 8 km) and none of it is statistically significant, so we make no claim about it. A popular fell nearby does not mean a full car park.
Distance is measured to a fell’s summit, not to its
trailhead — Glenridding is the Helvellyn car park, but Helvellyn’s summit is about
four kilometres away — which is why we report three distances rather than one.
All 20 car parks could be placed. Fell names whose search volume is
contaminated by something else entirely are excluded at source. This is our own join of two
datasets, not a figure the Authority released. Computed by
ingest_carpark_search_join.py.
All twenty, ranked
Seasonality is only half of it. The other half is sheer scale: Hawkshead takes 75,706 transactions a year against Threlkeld's 608 — a 125× spread across car parks in the same National Park.
| Car park | Transactions a year | August ÷ January | What that makes it |
|---|---|---|---|
| Hawkshead | 75,706 | 4.5× | quieter in winter |
| Waterhead, Ambleside | 62,884 | 7.9× | quieter in winter |
| Glenridding | 52,182 | 4.5× | quieter in winter |
| Brockhole | 46,095 | 14.2× | mostly a summer car park |
| Coniston Boating Centre | 35,256 | 12.0× | mostly a summer car park |
| Ruskin Avenue, Coniston | 34,189 | 5.0× | quieter in winter |
| Broadgate, Grasmere | 27,456 | 3.3× | quieter in winter |
| Pooley Bridge | 26,764 | 3.8× | quieter in winter |
| Buttermere | 20,551 | 3.9× | quieter in winter |
| Monk Coniston | 11,193 | 8.3× | mostly a summer car park |
| New Dungeon Ghyll | 9,466 | 2.7× | much the same all year |
| Brown Howe | 7,894 | 8.9× | mostly a summer car park |
| Coniston Old Station | 7,520 | 3.9× | quieter in winter |
| Ravenglass | 7,398 | 11.9× | mostly a summer car park |
| High Dam, Lakeside | 6,394 | 1.9× | much the same all year |
| Hammarbank, Windermere | 4,805 | 8.2× | mostly a summer car park |
| Beech Hill | 4,712 | 14.4× | mostly a summer car park |
| Cow Bridge, Hartsop | 4,668 | 3.0× | much the same all year |
| Station Coppice, Thirlmere | 3,983 | 4.3× | quieter in winter |
| Threlkeld | 608 | 2.3× | much the same all year |
Questions
What is the least touristy part of the Lake District?
Nobody measures that for the whole National Park, but the Authority’s own 20 pay car parks show where the crowds go. Of those 20, the busiest, Hawkshead, takes 75,706 paid parking transactions in an average year and the quietest, Threlkeld, 608: a 125× spread (LDNPA, FOI/2026.486, response 22 July 2026; the mean of 2023-24 and 2024-25).
The catch: 20 car parks are a fraction of the parking in the National Park, and a transaction is not a car or a person. The season moves it too: 4 of them, Cow Bridge, New Dungeon Ghyll, Threlkeld and High Dam, sell much the same all year, while the lakeside and visitor-centre car parks go quiet in winter.
Where this data comes from
The figures are paid parking transactions supplied by the Lake District National Park Authority under LDNPA, FOI/2026.486 (opens in new tab), responded 22 July 2026. The Authority formally accepted that car park usage is environmental information under EIR Reg 2(1)(b).
The most important caveat is the unit. A count here is a paid transaction, not a car and not a person. A permit holder does not appear. Someone parking free does not appear. Two tickets bought for one visit count twice.
Why the month chart shows a shape and not a comparison. July to December carry four years of usable data in this release; January to June carry three. So the bars near the top of this page are totals across the comparable months only, and reading one month against another off them would be measuring the release, not the year. Every ratio quoted in this piece is computed within a single year for that reason.
- A count is a paid transaction, not a car and not a visitor. Permit holders and anyone parking free do not appear.
- Jan-Mar 2026 is RingGo-only, a payment-channel subset, so it is left out of this monthly series.
- Apr-Jun 2022 is declared missing by the source; FY2021-22 arrived empty.
- Jul-Dec carry four comparable years and Jan-Jun only three, so seasonality is computed WITHIN a year. Pooling months inflates it by about a third.
- Hawkshead May 2025, and Cow Bridge before Mar 2024, are unexplained in the source and are excluded from comparisons.
Two things we could not explain
Two things in this release we could not explain, and did not quietly drop. Both were raised with the Authority; the request closed before an answer came, so they are published as open questions and excluded from every comparison above.
- Hawkshead, May 2025: 706 transactions, against 7,118 and 7,316 in the months either side. Roughly 90% down on its neighbours for one month only. Most likely a machine outage or a data-entry error, but the source does not say.
- Cow Bridge, July 2022 to March 2024: 21 consecutive months of zero, then a normal figure from April 2024. That is the signature of charging being introduced rather than of a car park getting busier - which would make its apparent growth a billing change, not more visitors. Unconfirmed.
What this data cannot do is tell you when a car park fills. That needs hour-of-day figures, which are the subject of a separate request due in September 2026. Nothing on this page should be read as advice about what time to arrive.
Re-cut from the source release by
ingest_foi_parking.py; every figure on this page is computed from
data/visitor-pressure/car-park-pressure.json and none is typed by hand.
Cite or reuse this
Grab the citation (HTML): paste this to credit the report with a link back.
Media & data enquiries: lee@hikes.guide — journalists and teams are welcome to quote these figures with a credit. The monthly release behind them is not offered for download: the Authority has not yet confirmed a re-use licence for it. The hourly figures are open data on the open data page.
Spot a data error? Request a correction — every figure here is sourced and dated, and genuine mistakes are fixed promptly.
This analysis was made from data obtained by freedom-of-information request. hikes.guide takes no funding from any parking operator or authority.